Pleasanton, the Tri-Valley and across California
Small business 401(k) and retirement plans that work for you and your team.
Save more as an owner, give your employees a benefit they value and meet California’s CalSavers requirement, with a fee-only fiduciary firm led by a CFA® charterholder. Start with a complimentary plan review.
Already offer a plan through payroll or a broker? Review my existing plan
You run the business. We help run the plan.
Most California employers with at least one eligible W-2 employee (other than owners) must now offer a qualified retirement plan or register with CalSavers. Penalties for not complying can reach $750 per eligible employee. Federal tax credits can offset part of the cost of starting your own plan, and employer contributions are generally tax-deductible.
What it takes from you: a short first conversation and a recent payroll summary. If you already have a plan, add its fee disclosure and latest Form 5500 (the plan’s annual government filing). We coordinate the setup, or any change of provider, with the plan provider and your payroll.
Serving businesses in Pleasanton, Dublin, Livermore, San Ramon, Danville and across California, in person or by video.
A plan designed for your business
We compare the options against your payroll, your team and how much you want to save as the owner, then recommend one design with the costs laid out in writing.
How we design retirement plansSetup and CalSavers support
We coordinate with the plan provider and your payroll, and walk you through certifying your CalSavers exemption, so you can meet the requirement.
CalSavers or your own plan?Ongoing oversight, every year
For 401(k) plans, we take fiduciary responsibility for choosing and monitoring the investments (as an ERISA 3(38) investment manager), so you are not making those fund decisions yourself. We also review fees, educate employees and meet with you at least once a year so the plan keeps fitting your business.
Your fiduciary duties as a plan sponsorFederal tax credits can cover much of the startup cost
Under SECURE 2.0, eligible employers with up to 100 employees can claim federal tax credits for starting a new plan. For the smallest businesses, they can offset a large share of the early cost, which CalSavers does not offer.
Startup costs
Up to 100% of eligible setup and administration costs for employers with up to 50 employees, capped at $5,000 a year for three years (the cap depends on how many eligible employees you have).
Employer contributions
Up to $1,000 per eligible employee toward what the business contributes, for up to five years, phasing down after year two.
Automatic enrollment
An extra $500 a year for three years when the plan automatically enrolls employees.
See a worked example of what a plan costs after credits
Eligibility depends on your business’s facts, and credits reduce the deduction for the same costs. Confirm with your tax adviser.
Leadership
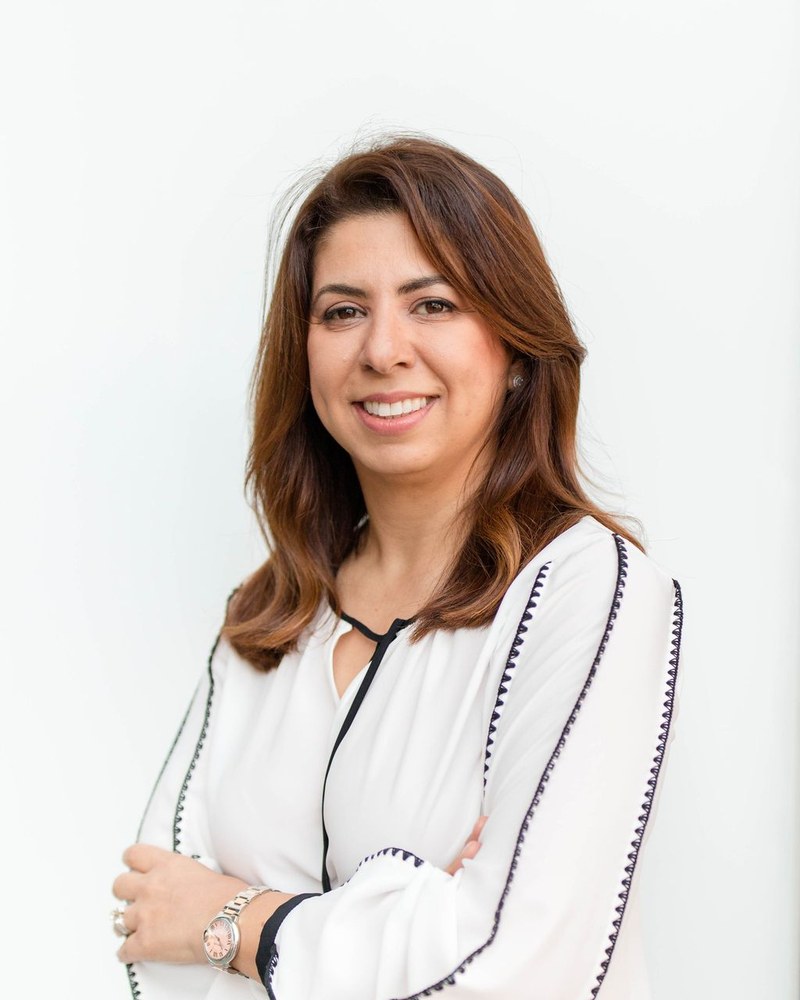
Led by a CFA® charterholder
Pleasanton Wealth was founded in 2018 by a CFA® charterholder with more than 20 years in investments and finance, including a career at Charles Schwab in San Francisco as a FINRA-registered representative.
Why owners work with Pleasanton Wealth
You work directly with the same CFA® charterholder from plan design and setup through every annual review.
As a fee-only fiduciary, we are paid only by clients, never by product sales. Our fees are simple and transparent: generally based on assets under management (AUM), and always disclosed in writing before you sign.
A 401(k) plan’s assets are held by the plan’s own custodian and recordkeeper, not by us, and each employee has access to their own account.
Request a complimentary plan review
Only your first name and email are required. We aim to reply within one business day, and there’s no obligation.
Fee-only fiduciary · CFA® charterholder · Public record: CRD #299123 at adviserinfo.sec.gov
Thank you. Request received.
An adviser will review it personally, and we aim to reply from samah@pleasantonwealth.com within one business day. Next comes a short conversation, then a written recommendation with every fee disclosed before you sign. There’s no obligation.
While you wait: get the retirement plan checklist.